New construction townhomes have been popping up in pockets of Sugar House alongside the neighborhood's older vintage bungalows, and buyers comparing the two are often surprised that closing costs don't look the same on both. Builder incentives, impact fees, and how the numbers get structured all shift depending on whether you're buying new or buying a home that's changed hands several times already.
Why New Construction Closing Costs Look Different
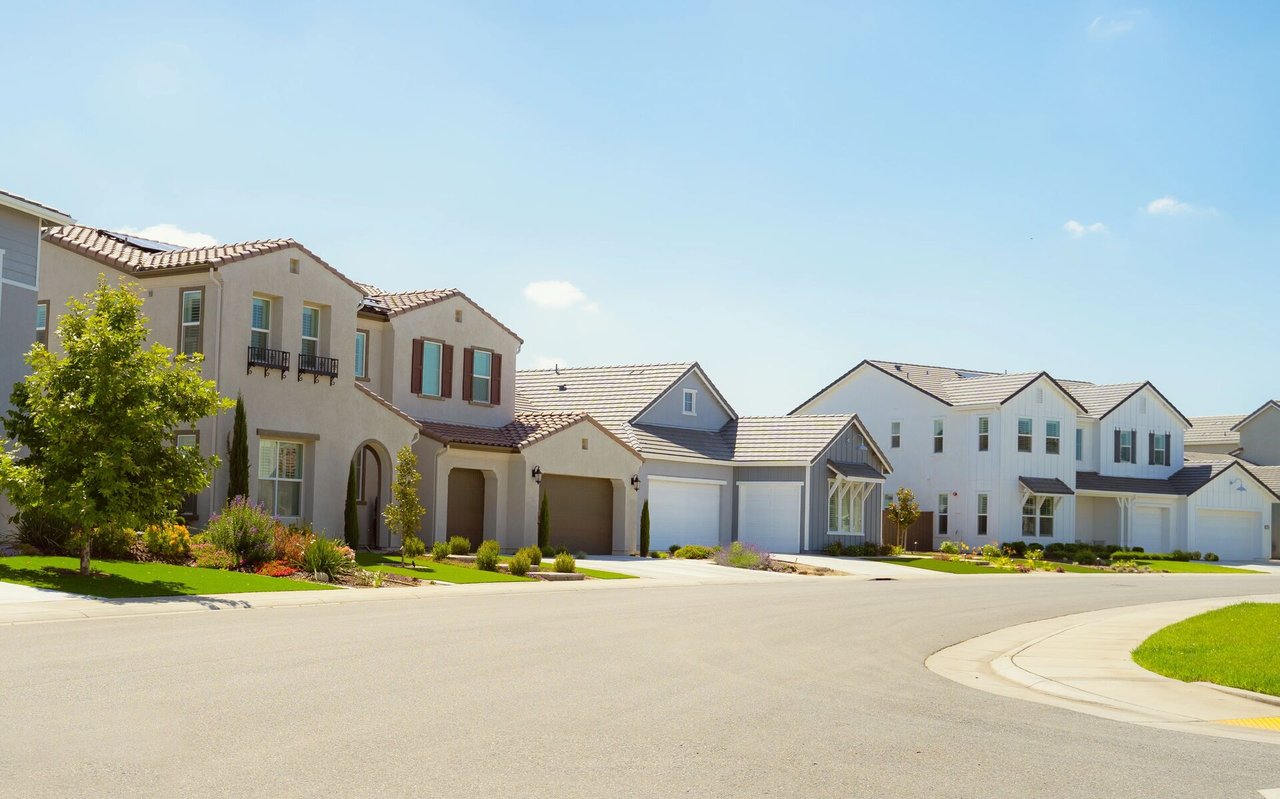
Builders in Sugar House's new townhome developments often offer closing cost credits or use a preferred lender incentive, which can genuinely lower your out of pocket cost at the table. But some of those same builders also charge fees a resale transaction wouldn't include, HOA setup fees for a brand new community, or specific warranty administration costs baked into the contract.
Why Vintage Bungalow Closing Costs Are More Predictable
On an established Sugar House bungalow, closing costs generally follow the standard Utah breakdown, title insurance, lender fees, prepaid items like property taxes and insurance, without the builder-specific line items new construction introduces. What you gain in predictability, you sometimes lose in negotiating leverage, since an individual seller may be less flexible than a builder trying to move inventory.
The Incentive Tradeoff Worth Understanding
A builder credit toward closing costs can sound like free money, but it's often tied to using the builder's preferred lender, whose rate may not be the most competitive one available to you. Run the numbers both ways, the credit plus their rate versus no credit with your own lender's better rate, before assuming the incentive is automatically the better deal.
What This Means for Your Sugar House Search
If you're comparing a new townhome to an older bungalow, I always recommend getting a full closing cost estimate on both before you decide, since the sticker price alone doesn't tell the real story of what you're bringing to the table.
Frequently Asked Questions
Are New Construction Closing Costs Always Lower than Resale?
Not necessarily. Builder credits can offset costs, but new communities sometimes add fees resale transactions don't have, like HOA startup costs. We compare both scenarios directly for you.
Should I Use the Builder's Preferred Lender for The Closing Cost Credit?
Only if their rate is actually competitive. We recommend comparing their offer against an independent lender before committing, since the credit isn't worth much if the rate is meaningfully higher.
Do Vintage Sugar House Bungalows Have Hidden Closing Costs?
Generally no hidden costs, but older homes can come with inspection-driven negotiations that affect your final numbers indirectly. We'll walk through a full estimate before you make an offer.
If you're weighing new construction against a vintage Sugar House bungalow, let's run real closing cost numbers on both before you decide.